Md. Zahirul Islam
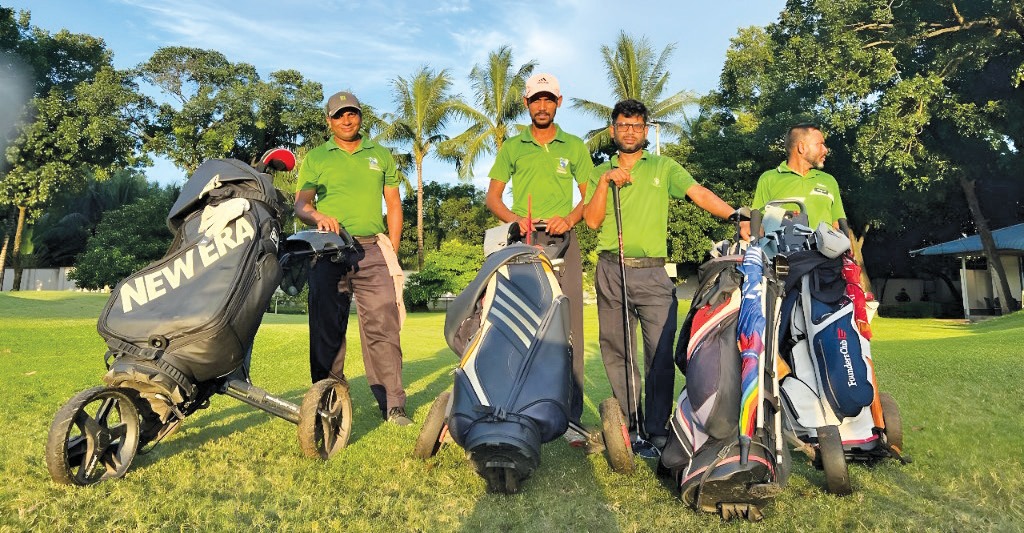
Every morning in Dhaka, golf caddies gather at the course gate before sunrise. Take Rahim, a father of three who has carried golfers’ bags at Kurmitola Golf Club for a decade. His workday starts with slinging a heavy golf bag over one shoulder and ends with a tired smile in exchange for a few hundred taka in tips. Like most caddies in Bangladesh, Rahim’s job is informal and insecure – no contract, no fixed salary, and crucially, no insurance or safety net if something goes wrong. One slip on the dew-soaked grass or a stray golf ball to the temple could end his ability to work, with devastating consequences for his family’s livelihood. This precarious reality is shared by hundreds of caddies across Bangladesh’s courses, and it highlights why a group insurance plan for caddies is not just prudent, but essential.
Life on the Edge of the Fairway – An Informal, Precarious Job
Being a caddie in Bangladesh is a quintessential informal job. Caddies are typically hired on a day-to-day basis, often treated as freelancers or independent contractors rather than formal employees. They show up each morning hoping to get a golfer’s bag to carry; if few players come or if it rains, many caddies return home empty-handed. There are no salaries, paid leave, or legal contracts – only the cash fee per round and maybe a tip. Earnings are low and erratic: even seasoned caddies earn only the equivalent of a few US dollars for hours of labor in the sun. (Bangladesh’s first golf star, Siddikur Rahman, famously started as a teenage forecaddie earning mere cents per round – a “pitiful” wage that speaks to how little caddying traditionally paid.)
This informal status leaves caddies excluded from any social safety nets or labor protections. In Bangladesh, a staggering 85% of all employment is informal, meaning workers like caddies generally have no access to formal social security programs or insurance. They lack the cushion of sick pay, medical coverage, or retirement benefits that formal workers might have. If a caddie falls ill or is injured, there is no employer-funded support – he simply cannot earn until he recovers, and his family may go hungry in the meantime. During the COVID-19 lockdown, for example, golf courses closed and caddies’ incomes vanished overnight; many suddenly needed charity to survive. Golf clubs and players in India had to raise emergency funds so that caddies could buy food, as “survival was a challenge” after the courses shut down. This episode starkly illustrated that without any built-in safety net, caddies live perpetually on the brink.
Low Pay and High Hazards on the Golf Course
Beyond low and unstable pay, caddying comes with real occupational hazards. Physical strain is constant: caddies haul 30–40-pound golf bags for 18-hole rounds, often multiple times a day, leading to chronic back and joint pain. They endure extreme weather – blistering summer heat, monsoon thunderstorms – with little shelter or rest. More acutely, there’s the danger of injuries on the job: being struck by an errant golf ball, slipping on wet terrain, or even the rare freak accidents one might not expect on a manicured course. Caddies often ride motorcycles or bicycles to work in the pre-dawn dark; some have been hurt or killed in road accidents during their commute. In India, the Caddies Welfare Trust reported that it has paid out insurance benefits to the families of multiple caddies killed in accidents on the way to work or by sudden illness, including a 23-year-old caddy who tragically died of cancer. Such stories underscore that caddies face life-threatening risks despite working in what appears to be a genteel sporting environment.
Yet in Bangladesh, if a caddie is injured or disabled, there is currently no system of compensation or insurance to cover treatment or lost income. A caddie could lose an eye to a flying golf ball or break an ankle in a fall, and he alone bears the consequences – paying medical bills out-of-pocket (if he can), and possibly losing his job if he can’t return quickly. For a workforce already living day-to-day, these hazards mean that every day’s work is a gamble with ruin.
Part of a Bigger Picture: Informal Workers and No Safety Net
The plight of golf caddies is one small window into the broader issue of Bangladesh’s huge informal sector. Over four-fifths of Bangladeshi workers are in informal jobs– from rickshaw pullers and day laborers to domestic helpers and, indeed, caddies. These workers form the backbone of the economy yet remain largely invisible in policy and unprotected in practice. Few informal workers have any kind of insurance or savings to fall back on. If disaster strikes – an accident, a serious illness, or a sudden loss of work – families can be plunged into destitution.
Successive governments have acknowledged this problem. Bangladesh’s National Social Security Strategy aims to extend coverage to informal workers, but implementation is slow and has not reached niche groups like caddies. In South Asia generally, three-quarters of workers rely on informal employment and have little ability to cope with shocks like COVID-19. The World Bank urges that countries design universal social protection for such vulnerable groups. For caddies, who typically operate outside any company payroll or union structure, innovative solutions are needed. Group insurance is one such solution – a way to bring at least basic financial protection to these workers even while they remain in informal employment.
No Insurance: What It Means to Caddies and Their Families
At present, Bangladesh’s caddies have virtually no insurance coverage. Neither government nor golf clubs offer any standard insurance scheme for them. Unlike many formal sector jobs (or professional athletes), caddies don’t get health insurance, accident insurance, or life insurance as part of their work. This absence is felt in every injury and funeral: if a caddie twists his knee and can’t work for a month, he likely earns nothing in that time and must pay for any treatment himself. If a long-time caddie dies suddenly, his family not only loses their breadwinner but also receives no death benefit or pension – a double blow often resulting in extreme financial hardship.
For example, caddies at one Dhaka club informally report that if one of them gets hurt, the others might pass the hat around to collect a bit of money, or a kind club member might offer a donation – but these ad hoc gestures are no substitute for a proper insurance safety net. The psychological stress is immense: caddies work knowing that one stroke of misfortune could cost them everything. As Rahim describes it, “Every day I step on the course, I pray nothing happens to me. If I break my leg today, tomorrow my children won’t eat.” This constant fear is the flip side of the freedom that comes with informal work.
Group insurance could fundamentally change this equation. By pooling caddies together – for instance, all caddies of a club, or across the country – an insurance scheme can provide coverage for accidents, injuries, illness, or death at an affordable collective premium. It would mean that if Rahim is hurt or falls sick, his treatment could be paid for and his family might get some income support during his recovery. If the worst happens and he dies, a payout could support his wife and children in the difficult months and years that follow. In short, insurance would replace fear with a measure of financial security and dignity for those who spend their lives serving golfers.
Learning from Neighbors: How Other Countries Protect Their Caddies
Bangladesh wouldn’t be the first to consider protecting caddies – there are lessons and precedents from other countries in Asia. In India, for example, golf clubs and philanthropists set up the Caddies Welfare Trust (CWT), a nationwide initiative to support caddies. A key part of CWT is group insurance: every caddie is required to purchase a basic life insurance policy for a token premium (around ₹200 per year), and the trust supplements this with a group policy that covers each caddie for up to ₹130,000 in case of natural death and ₹175,000 for accidental death. This insurance has already made a difference – over a dozen caddie families received payouts when tragedy struck, including families of young caddies who died in accidents or of illness. In addition, some Indian golf clubs now also provide health insurance or medical expense funds for their regular caddies. These measures have not only saved families from destitution but also improved caddies’ morale and loyalty. It shows that with minimal cost, a safety net can be built.
In the Philippines, lawmakers recognized the vulnerability of caddies and proposed a Golf Caddies Welfare Fund to provide compensation for work-related injuries, sickness, or death. The draft House Bill explicitly aims to ensure caddies’ well-being in cases of accidents, illness or fatality on the job. It seeks to establish a contributory fund – possibly financed by small fees on golfers or club contributions – that would act as an insurance pool for all caddies. While this legislation is still in process, it reflects a growing understanding that caddies deserve formal protection despite their informal status.
Meanwhile, Thailand offers a glimpse of a market-driven approach. With a booming golf tourism industry, Thai insurance companies have introduced specialized “Caddie Insurance” packages to cover accidents. These plans provide caddies with benefits for accidental injuries, disabilities, and death, and even cover scenarios like being assaulted on the job or riding as a passenger on a motorcycle (a common mode of caddie transport). Essentially, for a modest premium, a Thai caddie can get coverage that will pay out cash benefits to them or their family if they get hurt or killed in an accident. Many Thai golf courses require hiring caddies for each round, and some courses have insurance in place to cover caddie-related mishaps, which provides reassurance to both caddies and visiting golfers. The Thai example shows that insurance for caddies is feasible and readily available when there is awareness and demand for it.
These international examples – India’s collective insurance via a welfare trust, the Philippines’ legislative push for a caddie welfare fund, and Thailand’s targeted insurance products – offer ideas for Bangladesh. They demonstrate that protecting caddies is both a moral responsibility and a practical possibility. Crucially, they show that insurance need not be expensive: when spread across many caddies or supported by golf stakeholders, the cost per person is low, but the impact is life-changing.
A Way Forward: Group Insurance for Bangladesh’s Caddies
To uplift Bangladesh’s golf caddies, a group insurance scheme could be instituted through a collaboration of golf clubs, the national golf federation, insurance providers, and possibly the government. Here’s how it might work:
- Organize Caddies into Groups or Associations: Caddies at each golf club (or city/region) could form an association or register under a common group. This would make it easier to enroll them in a collective insurance policy and to represent their interests. In fact, the Philippine proposal requires caddie associations to register and be the conduit for benefits – a model Bangladesh could emulate.
- Negotiate Affordable Group Policies: With caddies grouped, an insurance company could offer a bulk accident and life insurance plan covering all members. The premium could be negotiated to a low rate (given the relatively young, able-bodied demographic of caddies), and could be funded by a mix of contributions: a small portion from caddies’ own fees (say, 20–50 taka per week), matching contributions from golf club revenues or members, and even sponsorships or government subsidies. The cost per caddie might end up only a few hundred taka per year – a tiny fraction of what a single golf round costs a player – yet it would buy each caddie and their family a measure of protection.
- Cover Core Risks: The group insurance should prioritize accidental death and disability coverage, and basic health insurance. For example, it could insure each caddie’s life for a lump sum (to be paid to their family if they pass away or are permanently disabled) and provide a fixed amount for medical expenses if they are injured on the job. Even a payout of ৳100,000-200,000 (around $1,000–$2,000) for a caddie’s death or disability would be significant in Bangladesh – enough to cover hospital bills or support a family through transition. This is in line with what India’s CWT provides (roughly ₹130,000–175,000, as noted), which has proven its value. Health insurance might involve tie-ups with hospitals or clinics for discounted care, or inclusion in a national health scheme if possible.
- Policy Support: The government and sporting authorities can support this initiative by recognizing caddies as workers who deserve social protection. Just as Bangladesh has schemes for garments workers or farmers, it can encourage or mandate that golf clubs take responsibility for caddies’ welfare. This could mean offering tax breaks to clubs that insure their caddies, or even making it a condition of club licensing that caddie insurance is provided. Moreover, aligning with national social insurance programs (as Bangladesh is considering extending to informal sectors) could amplify the impact. The informal sector won’t be formalized overnight, but interim measures like group insurance can bridge the gap, ensuring workers aren’t left totally vulnerable.
- Awareness and Buy-In: Key to success will be making both caddies and golfers aware of the benefits. Caddies might initially worry about any fee deduction for insurance, so success stories from elsewhere (like how Indian caddies’ families received payouts that saved them from hardship should be shared. Golfers and clubs should be sensitized that caddies are integral to the game – much as caddies support golfers on the course, the golfing community must support caddies off the course. Appeals to solidarity, perhaps through golfer-caddie trust funds or charity tournaments, can raise initial funds and awareness. Ultimately, a well-implemented scheme would become self-sustaining through small contributions and would foster a more loyal, secure caddie workforce.
Conclusion: Safety, Dignity, and a Better Game for All
Golf is often called a gentleman’s game, and part of that ethic is treating those who make the game possible with fairness and respect. In Bangladesh, golf caddies have labored in the shadows – indispensable to players’ enjoyment, yet with their own needs overlooked. They carry more than just golf bags; they carry the economic burden of their families on those narrow shoulders. Group insurance offers a ray of hope. By cutting in half the fear that any day’s work could be their last healthy one, insurance would give caddies and their loved ones a basic security they have never known. It would mean Rahim can walk the fairways without a constant knot of worry in his stomach. It would mean a caddie’s wife can sleep a little easier knowing that if her husband doesn’t come home from the course one day, she won’t be utterly destitute.
Emotionally and narratively, the impact is profound: caddies who feel valued and protected are likely to be more motivated, providing better service and enriching the golfer’s experience. In the longer run, such a policy could encourage more young people to become caddies (and perhaps the next Siddikur Rahman will emerge from their ranks), knowing it’s not a dead-end trap of poverty. It’s often said that the measure of a society is how it treats its most vulnerable. In the micro-society of a golf club, the caddie is the vulnerable backbone. Ensuring group insurance for caddies in Bangladesh would send a powerful message that their well-being matters – that the people who have our back on the golf course will have society backing them up in life’s roughest hazards.
By learning from neighbors and taking initiative, Bangladesh’s golfing community and policymakers can turn this vision into reality. Group insurance for caddies isn’t just about money or policy – it’s about dignity, justice, and doing the right thing for those who silently make our leisurely walks on the fairway possible. It’s time to extend a helping hand to the caddies, so that the next time they say “good shot, sir!”, we can be confident that they too have a fair shot at a secure and hopeful life.